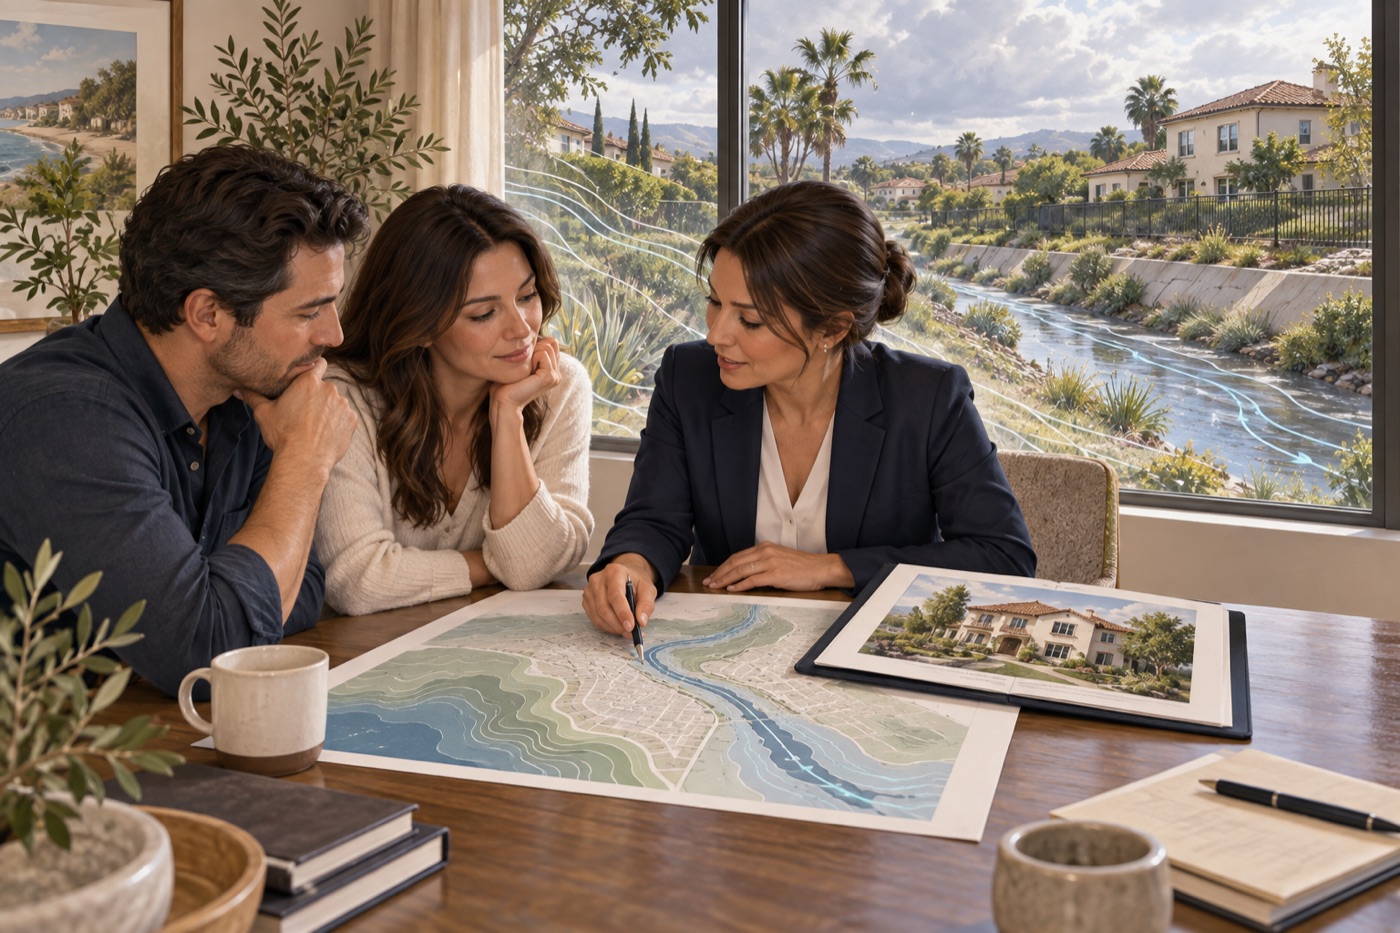
In Orange County, water is part of the landscape people love. It is also part of the risk buyers sometimes underestimate.
Flood questions are not limited to a home with an ocean view. Drainage channels, low-lying streets, creeks, slopes, debris, changing runoff, and severe storms can matter inland too. Two homes in the same ZIP code can have very different answers.
That is why the future of the National Flood Insurance Program keeps appearing in Washington's real-estate discussions.
What the federal program does
The National Flood Insurance Program, commonly called NFIP, makes flood coverage available in participating communities and supports the mapping used in many lending and insurance decisions.
Congress has repeatedly renewed the program for limited periods. The National Association of REALTORS® is asking for a longer-term reauthorization and reforms, arguing that repeated short extensions create uncertainty for homeowners, buyers, lenders, and real-estate transactions.
This is not a distant policy issue when a closing depends on coverage.
A flood zone is important—but it is not the whole story
FEMA's Flood Map Service Center is the official place to begin researching mapped flood hazards. A lender may require flood insurance for certain properties securing federally backed financing in designated high-risk areas.
But a map designation should not be treated as a guarantee of safety. Flooding can occur outside the highest-risk zones, and maps cannot tell a buyer everything about a property's drainage, prior water intrusion, grading, nearby improvements, or future conditions.
The reverse is also true: being in a mapped area does not tell you the exact cost or terms of coverage. That requires an address-specific insurance conversation.
Questions to ask before the deadline pressure begins
When a property becomes a serious possibility, consider asking:
- What does the current FEMA map show for this address?
- Has the structure or parcel received a Letter of Map Amendment or revision?
- Is flood insurance required by the proposed lender?
- What are the available policy limits, deductibles, exclusions, and waiting periods?
- Is there an elevation certificate or other relevant property record?
- Has the seller disclosed past flooding, drainage work, or insurance claims?
- Are there nearby public drainage or infrastructure projects?
Review disclosures and inspections with the appropriate professionals. If coverage matters to the purchase, obtain a written quote early rather than relying on a rough estimate.
The human reason to investigate
Buyers are often carrying a great deal of excitement by the time they write an offer. They have already pictured the dining table and decided which room gets the morning light.
Due diligence is not meant to take that joy away. It is meant to protect it.
A flood map, insurance quote, and careful property review may not be the memorable parts of buying a home. They are part of making sure the home remains a place of comfort after the keys change hands.
A property-specific next step
Policy can shape the market, but a good decision still belongs to the property and household in front of you. Raveena can help you organize the real-estate questions, compare documented property facts, and identify which questions belong with a tax adviser, attorney, lender, insurance professional, contractor, government agency, or other qualified expert.
Sources and further reading
Reviewed by Raveena Ashar
Orange County real estate professional · California DRE #01936601 · Rise Realty